
Best Equipment Financing Companies for U.S. Businesses
Compare equipment financing companies for U.S. businesses, including options for used machinery, credit needs, funding amounts, and application tracking.
A large equipment purchase can put pressure on cash you need for payroll, fuel, or the next job. The best equipment financing companies help you spread that cost, but the right fit depends on the machine, your cash flow, and how quickly you need to move.
Here are five options for U.S. business owners, starting with Dengaro’s online application and status tracking for financing requests from $15,000 to $2 million.
Table of Contents
- Dengaro — Online applications with status tracking
- Crest Capital: Loans and leases for a range of business equipment
- National Funding: Equipment financing and leasing up to $150,000
- DLL Group: Equipment financing backed by long-standing industry experience
- United Capital Source: A financing option to investigate for quick turnaround
- Compare equipment financing companies by fit, terms, and eligibility
- Frequently asked questions
- Conclusion
1\. Dengaro — Online applications with status tracking
Dengaro is an online equipment financing application platform for U.S. businesses requesting $15,000 to $2 million for new or used equipment. It’s a strong fit when you want one place to submit a request and follow its progress, especially if you’re comparing financing paths for a machine purchase.
For a contractor, that can matter when a job depends on replacing a skid steer or adding an excavator. You can submit the request online, track your application, and keep the financing process in view while you handle the equipment purchase. Dengaro provides operational review and controlled delivery to financing providers. The providers make credit decisions and determine any offer.
Dengaro supports requests for both new and used business equipment. That gives you a route to explore financing for a used machine without assuming every lender handles pre-owned assets the same way. Your application still needs to describe the machine and the purchase clearly, since equipment details and the overall transaction can affect a provider’s review.
If you’re getting ready to apply, gather the invoice or quote, the equipment’s details, and your business information. The equipment financing application checklist can help you prepare. Submitting an application doesn’t guarantee approval, and financing is subject to provider approval.
Dengaro’s main distinction is process visibility. You can apply online and track your application rather than treating the initial submission as the end of your role. For contractors handling a time-sensitive purchase, that can make it easier to keep the financing request organized alongside the job schedule.
2\. Crest Capital: Loans and leases for a range of business equipment
Crest Capital is a national equipment financing company for small and mid-sized businesses. Crest Capital offers loans or leases for equipment, vehicles, or software, with financing amounts from $5,000 to $500,000.
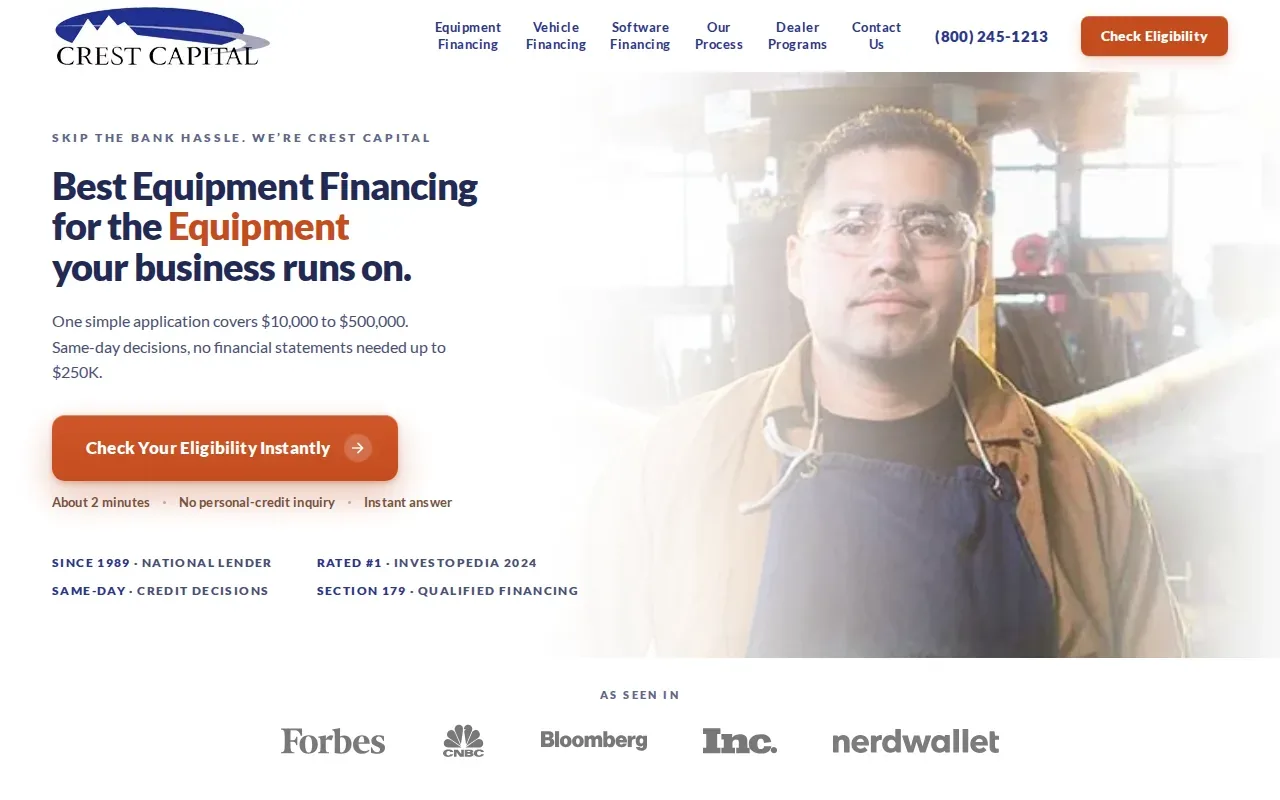
The company’s equipment financing information covers new and used purchases, including equipment bought from a dealer or another business. That can suit an established company shopping for a specific machine while choosing between owning it through a loan or using a lease structure.
Crest Capital describes fixed-rate financing. Fixed payments can make monthly cash-flow planning easier because the payment amount stays the same for the term.
For requests up to $250,000, Crest Capital says it doesn’t require tax returns or other financial statements. That may reduce the paperwork for some applicants, but you should still have the purchase details and business information ready. The financed equipment itself can serve as collateral, and the company says it doesn’t require a blanket lien on most transactions.
Consider Crest Capital when your request fits within its stated amount range and fixed payments suit your cash plan. Compare the full payment structure and any loan or lease terms before deciding. A quick decision is useful only if the financing also fits the machine’s working life and expected revenue.
3\. National Funding: Equipment financing and leasing up to $150,000
National Funding is a small business lender with equipment financing and leasing up to $150,000. It may fit a business with a smaller purchase or a construction company that needs to replace a machine without using all its cash reserves.
The company’s materials include new and used equipment. Its construction equipment examples include excavators, skid steers, boom lifts, and dump trucks. National Funding also describes equipment financing for trucking, health care, agriculture, food service, and technology. That range gives business owners several common equipment types to consider within the stated amount limit.
National Funding says businesses need at least six months in operation and $250,000 in annual sales for equipment financing. Those requirements help you screen for fit before preparing a full request. The company also describes a quick online application and a dedicated U.S.-based Funding Specialist who reviews the file.
National Funding offers financing or leasing up to $150,000, subject to approval and the details of the financing offer.
A loan and a lease don’t end the same way. National Funding explains that a loan leads to ownership after you repay it, while a lease may let you renew, return, or buy the equipment at the end. Think through how long you plan to use the machine before picking a structure. If you expect to keep it for years, ownership may matter more than a lower initial payment.
4\. DLL Group: Equipment financing backed by long-standing industry experience
DLL Group is an equipment financing company with 50 years of experience. It may be worth investigating if your equipment purchase is part of a financing relationship arranged through a business partner.
DLL describes its work in terms of understanding partner needs and providing financing solutions around the world. That partner focus is different from choosing a provider based only on an online application or a stated funding limit. If a manufacturer, dealer, or other business partner points you toward DLL, ask how the financing fits the equipment you’re buying and the way your business plans to use it.
Before you move forward, get the offer’s full payment schedule and clarify what happens at the end of the term. For a construction business, the useful question is whether the financing period lines up with the machine’s expected time on the job. A long term may ease monthly cash demands, but the machine should remain useful while you’re still paying for it.
DLL may be an option when a partner channel connects it to the equipment purchase. Compare the written terms with another suitable option before you commit, especially if you need a specific amount or have a firm delivery date.
5\. United Capital Source: A financing option to investigate for quick turnaround
United Capital Source is a financing marketplace that reports a typical turnaround of 24 to 72 hours and same-day funding capability. It may suit a business owner facing an urgent equipment need, though the stated turnaround isn’t a guarantee for every application.
United Capital Source packages an application and matches it with financing providers. It doesn’t lend its own capital. For an owner who wants to explore more than one possible provider, that approach can make a single application useful across a broader financing search.
The company’s equipment financing information describes loans and leases. With a loan, you repay the balance and own the equipment at the end. A lease may keep payments lower, with an option to buy or upgrade depending on the agreement. Check the contract’s end-of-term terms rather than relying on a general description of leasing.
Speed should be weighed against the complete cost and fit. Compare the payment amount with the machine’s expected contribution to cash flow. If the equipment won’t earn revenue right away, make sure the first payments won’t strain payroll or other operating costs during that gap.
United Capital Source is one to ask about when timing is tight and you want to consider a marketplace route. Review the specific provider, repayment term, and any equipment-related conditions in the final offer before accepting it.
Key Takeaway: A quick financing decision can help keep a job moving, but the payment schedule still needs to fit your cash flow.
Compare equipment financing companies by fit, terms, and eligibility
A provider’s headline amount or speed won’t tell you whether a deal fits your business. Compare each option against the purchase amount, machine type, eligibility rules, and the cash you need to keep available after closing.
Company| Best fit to consider| Stated amount or timing| What to check ---|---|---|--- Dengaro| Online application and status tracking for new or used equipment| $15,000 to $2 million| Provider approval and the terms offered for your request Crest Capital| Small or mid-sized businesses comparing equipment loans and leases| $5,000 to $500,000; many decisions within hours| Fixed payment terms and collateral details National Funding| Businesses with at least six months in business and $250,000 in annual sales| Up to $150,000; funding as fast as the next business day| Loan versus lease and the end-of-term choice DLL Group| Businesses whose equipment purchase comes through a partner relationship| Specific amount depends on the transaction| Written payment schedule, eligibility, and term United Capital Source| Owners exploring marketplace financing when timing matters| Typical turnaround of 24 to 72 hours; same-day funding capability| Which provider makes the offer and its full terms
Start with the machine and the amount
Write down what you’re buying, whether it’s new or used, and the full purchase cost. A seller’s invoice or quote helps connect the financing request to a real asset. For used equipment, include clear details about the machine and its condition so a financing provider can review the specific purchase.
Then compare the amount you need with each provider’s stated range. Dengaro’s requests start at $15,000 and go up to $2 million. Crest Capital’s stated range is $5,000 to $500,000, while National Funding’s equipment limit is $150,000. Those ranges can narrow the field, but they don’t establish that you’ll qualify.
Check eligibility without treating credit as the only factor
Lenders may consider your personal credit, time in business, revenue, cash flow, and the equipment itself. FICO is a personal credit score used in many lending reviews. A lower score can affect the terms or the providers willing to review an application, but it doesn’t tell the whole story by itself.
Be ready to explain how the machine supports the business. A skid steer tied to a new contract has a clear business use; a replacement excavator may help you avoid downtime on current work. Providers may also review business bank activity and the ability to make payments from operating cash flow.
If you’re comparing offers, distinguish an initial application review from a firm financing offer. Ask whether a credit inquiry is involved and when it may happen. You can also review how equipment financing credit checks may work before you submit information.
Choose a loan or lease based on how long you’ll use the asset
An equipment loan is built around buying the asset. You repay the loan over time, and ownership typically follows once the balance is paid. The equipment often secures the loan, so missed payments can put that asset at risk. A lender may also ask for a personal guarantee or other terms, depending on the offer.
A lease gives you use of the equipment under an agreement. At the end, the contract may allow you to return it, renew the lease, or buy it. That can make sense if you expect to replace equipment often or want to avoid owning a machine that may lose usefulness quickly. Read the buyout and return terms carefully.
Loan payments can be fixed or variable depending on the agreement. Fixed payments make the amount easier to plan around. With variable terms, ask how changes are calculated and how they could affect the total amount you repay. Don’t compare offers by monthly payment alone. A longer term can lower the payment while increasing how long the business carries the debt.
Prepare the application before the equipment is needed
Gather the purchase quote or invoice, equipment make and model, seller information, and business financial details. Depending on the provider and request, you may also need tax information, bank statements, or owner details. A complete file can reduce back-and-forth while a provider reviews the transaction.
Use Dengaro’s online equipment financing application to submit a request and track its status. The financing provider reviews the request and decides whether to make an offer. Compare the complete terms before accepting, including the payment schedule, fees, down payment, collateral, and any end-of-term requirements.
Pro Tip: Match the repayment term to the years you expect the machine to earn for your business, not just the smallest monthly payment you can find.
Keep tax and credit questions specific
Equipment financing can affect taxes and business credit differently based on the agreement and your business situation. Don’t assume a payment is deductible or that an account will report to a particular credit bureau. Ask your tax professional how the proposed loan or lease applies to your business, and check the provider’s contract for credit reporting terms.
For a new business, a short operating history may make approval harder because there’s less revenue history to review. A clear equipment quote and a realistic cash-flow plan can help explain the request, but they can’t replace a provider’s eligibility rules. If you’re newer to business, compare the required time in operation before spending time on a full application.
For broader research, separate lender types by what they tend to offer. Banks and credit unions may be worth asking about if you have strong financials and time for a more involved review. Online financing companies can have simpler application flows, while leasing companies may fit assets you expect to replace. SBA-backed financing is another category to ask a qualified lender about; eligibility and process depend on the program and provider.
Ready to compare financing for your equipment purchase? Review equipment financing with Dengaro, then apply online and track your application.
Frequently asked questions
What is equipment financing?
Equipment financing is funding used to buy or lease equipment for a business. With a loan, you make payments over an agreed term, and the equipment often secures the loan. Once you repay it, you typically own the asset. A lease lets you use equipment under a contract, with end-of-term options set by that agreement.
Can I finance used construction equipment?
Yes, some equipment financing companies consider used machinery. Dengaro accepts requests for new or used business equipment, and Crest Capital and National Funding also describe financing for new and used equipment. The provider reviews the specific asset and transaction, so prepare the seller’s quote and clear equipment details before applying.
What do lenders look at for equipment financing?
Lenders may review your credit, time in business, revenue, cash flow, and the equipment being financed. The exact requirements vary by provider. For example, National Funding states a minimum of six months in business and $250,000 in annual sales for its equipment financing. Meeting a stated requirement doesn’t guarantee approval.
Is equipment financing better than leasing?
Neither choice is always better. A loan can suit you if you want to own the equipment after repayment. A lease may fit if you want use of the asset with the option to return, renew, or buy under the contract. Compare the total cost and end-of-term rules, then consider how long the machine will remain useful.
How fast can equipment financing be approved?
Timing depends on the provider and your application. Crest Capital says most credit decisions arrive within a few hours and almost always within one business day. United Capital Source reports a typical turnaround of 24 to 72 hours and same-day funding capability. These are not guarantees; a complete file and provider review affect timing.
Conclusion
For a U.S. business financing $15,000 to $2 million in new or used equipment, Dengaro is a useful starting point because you can apply online and track your application. Gather the machine quote and business details, then start your equipment financing request and review any provider offer before accepting.