
Best Farm Equipment Financing Options for 2026
Compare farm equipment financing for new and used machines, with details on loan terms, eligibility, application steps, and cash-flow trade-offs.
A new tractor or used skid steer can solve a pressing work need, but the payment still has to fit your cash flow. Farm equipment financing options vary: some focus on farm machinery, while others can cover a wider range of business equipment. Here are five options and the details to weigh before you apply.
We analyzed 43 comments from Reddit and YouTube about farm equipment financing and found that 33% mentioned qualifying criteria and suitable lenders.
Table of Contents
- Dengaro
- AgDirect: Farm equipment loans and leases
- Farm Credit Express: Financing through participating dealerships
- Farm Equipment Loans by FBN: A farm-focused loan option
- Ameris Bank: Bank financing to compare with specialty options
- How to compare farm equipment financing offers
- Farm equipment financing FAQ
- Conclusion
1\. Dengaro
Dengaro is an online equipment financing application platform for U.S. businesses seeking $15,000 to $2 million for new or used business equipment. That can suit farm owners and contractors considering a higher-cost machine, such as an excavator or skid steer, who want to submit a request online and track its progress.
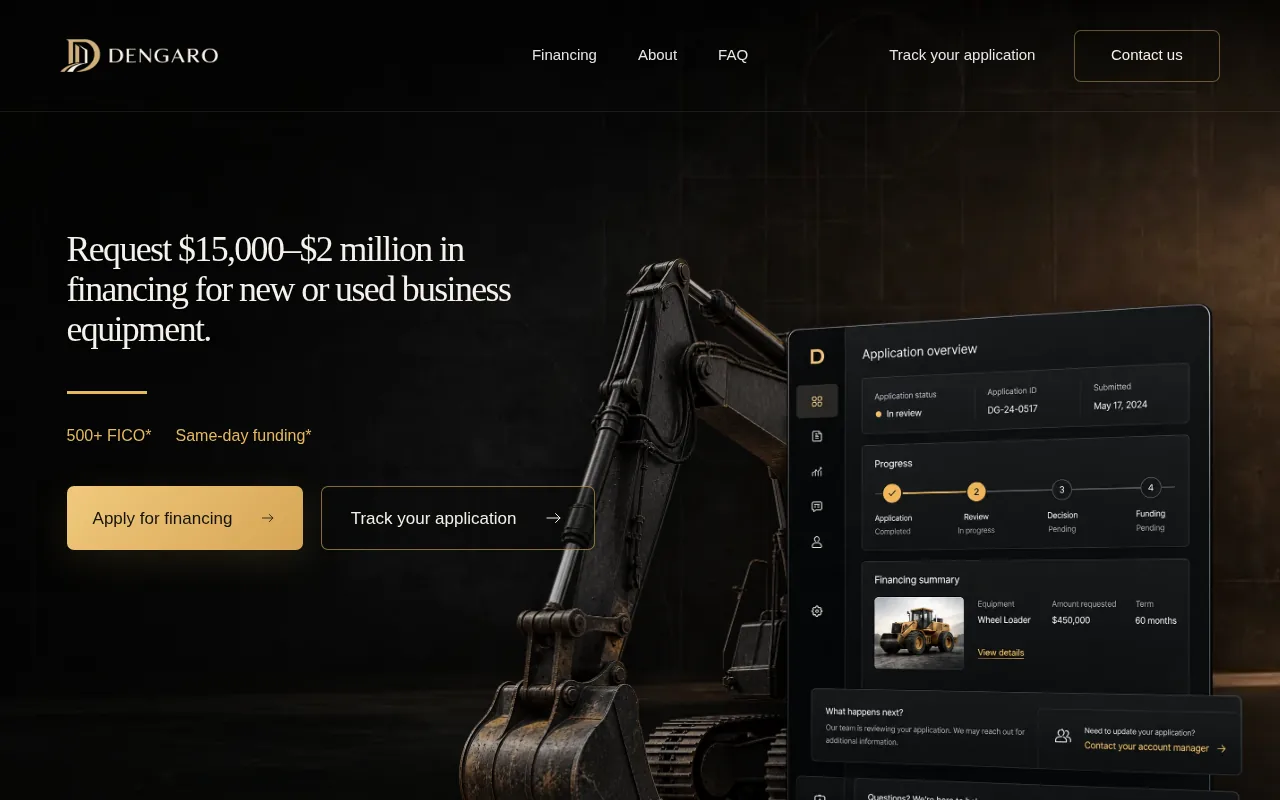
When you apply, include the equipment details and expected price, along with accurate business and owner information. A lender may also ask for an invoice or more records to review the deal. Clear paperwork can help you respond when a provider asks for more information.
Dengaro lets you apply online and track your application. Its site says requests are subject to provider approval, so submitting an application doesn’t guarantee financing or final terms. For a closer look at the amount and equipment the platform is intended for, see Dengaro’s equipment financing details.
If you’re comparing offers, look beyond the payment amount. Check the total repayment, any fees, the term, and whether the scheduled payments fit your farm’s income cycle. A larger financing request can preserve cash for fuel, seed, repairs, or payroll, but the debt still needs to fit projected income.
2\. AgDirect: Farm equipment loans and leases
AgDirect offers financing and leasing for new and used agricultural equipment. When comparing options, consider whether a loan or lease aligns with the machine you need and your business plans.
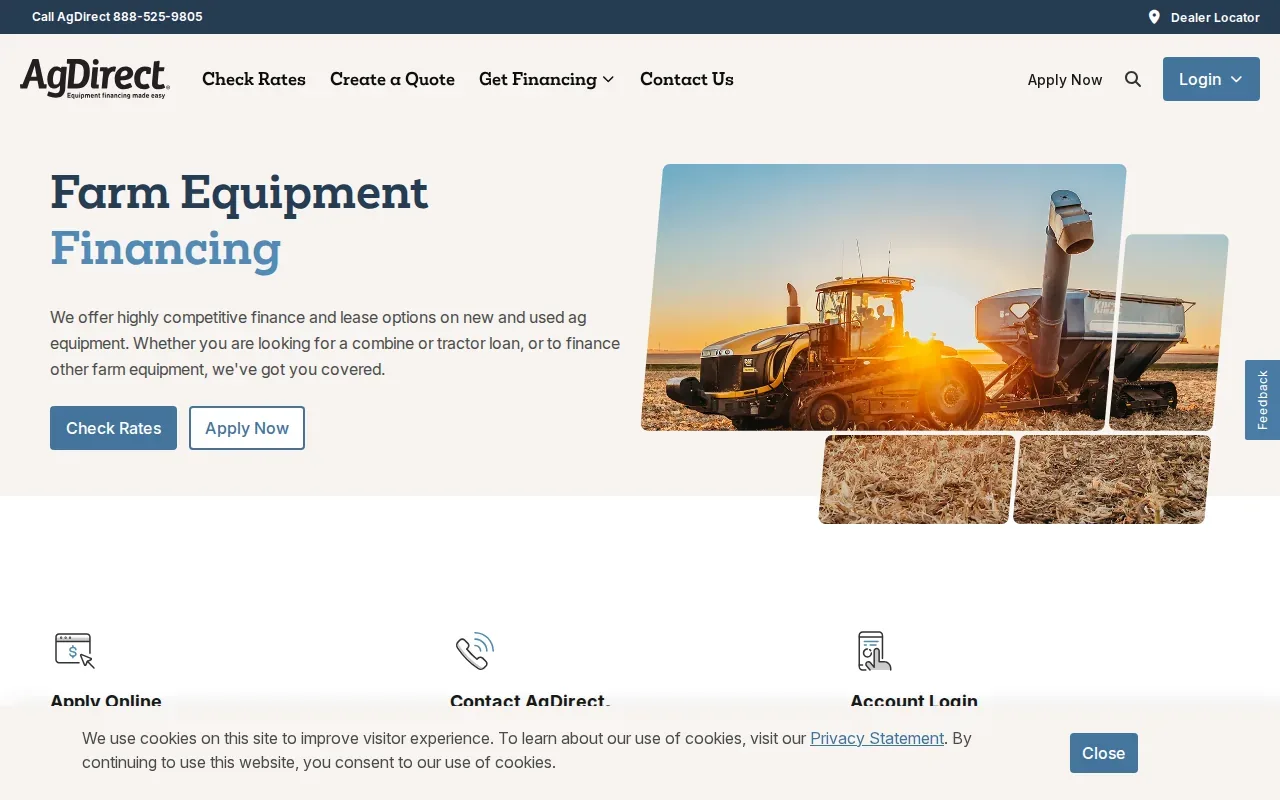
For most equipment, repayment terms range from two to seven years; pivots may have terms up to 10 years. Eligible borrowers might qualify for $0 down. Those are possibilities, not automatic terms, so compare the written offer against the equipment price and the cash you need to keep in reserve. For a farm business, weigh payments against cash available for other operating costs and consider whether the repayment period fits your equipment plans. If you’re considering a used machine, confirm its eligibility and any credit requirements before relying on a quoted structure.
Account for timing if the seller has a deadline or the machine is needed for a narrow work window. Comparing financing options in advance can help you evaluate the written terms against your equipment needs and schedule.
AgDirect also has lease options. When comparing any offer, don’t focus on a rate alone. Check the term, fees, any rebate you’d give up, and the full payment schedule. A lower monthly payment can still mean a higher total cost if the term is longer.
Key Takeaway: AgDirect is a farm-focused choice to compare when you’re buying or leasing equipment.
3\. Farm Credit Express: Financing through participating dealerships
Farm Credit Express provides equipment loans through participating dealerships. It may suit buyers who want to discuss financing while choosing a machine, rather than arrange a separate lender conversation first.
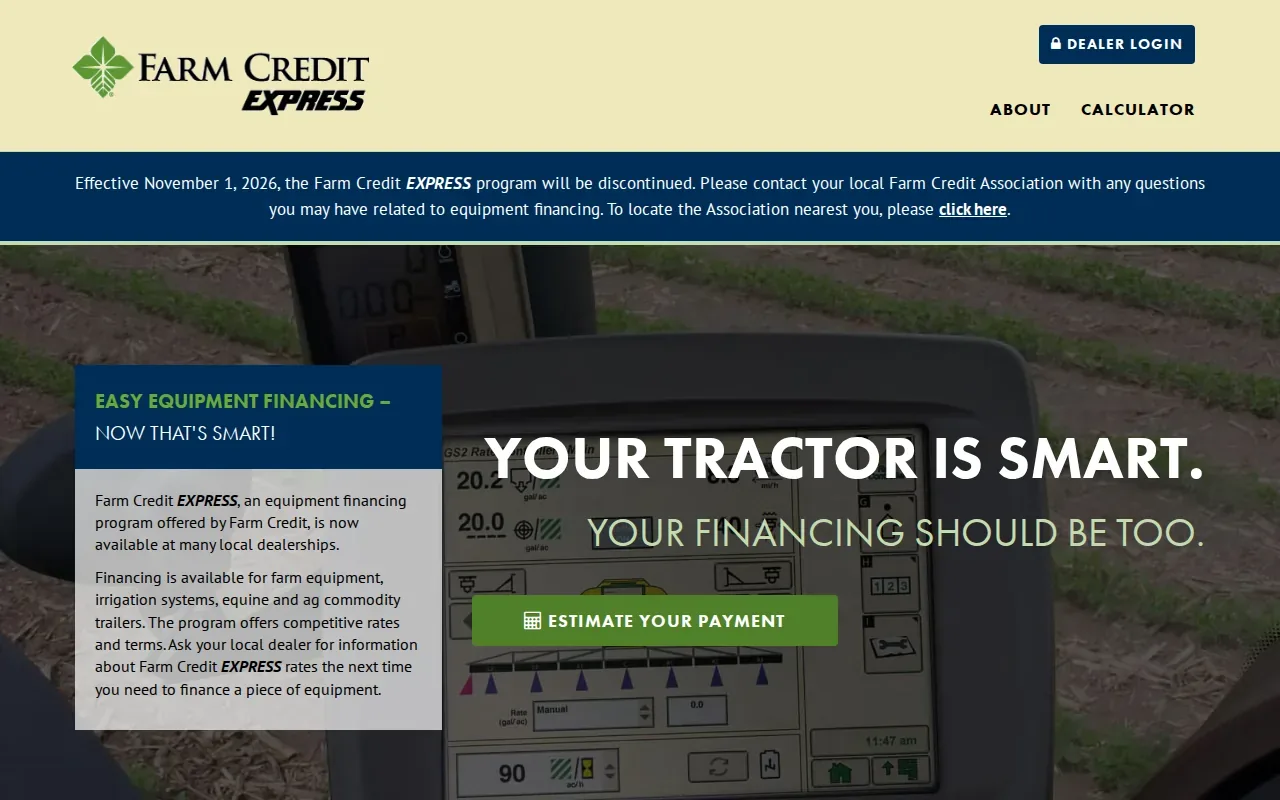
Approval might come in as little as a few minutes, though timing depends on the application and the review. Farm Credit Express borrowers are also eligible for the lender’s profit-sharing program. Ask the participating dealership to explain how the program applies to your transaction and which payment terms are available.
Dealership financing can be convenient, but convenience isn’t a substitute for comparing the whole deal. Ask for the equipment price separately from the financing terms. Then compare the total amount paid, payment dates, and any down payment against a bank or other written offer.
Government-backed lending is another route for some farm operations. Some farm operations may also explore government-backed financing, though program eligibility and permitted uses vary. You can review the FSA Farm Operating Loans page for more information. For equipment only, compare the application scope and expected timing with the machine seller’s deadline.
Farm Credit Express is worth considering when your preferred equipment seller participates and you want a financing decision tied to the purchase process.
4\. Farm Equipment Loans by FBN: A farm-focused loan option
Farm Equipment Loans by FBN is a farm-focused option to include in your comparison. Before choosing it, focus on the written terms for the specific machine you plan to buy, rather than relying on a general headline or a quoted monthly payment.
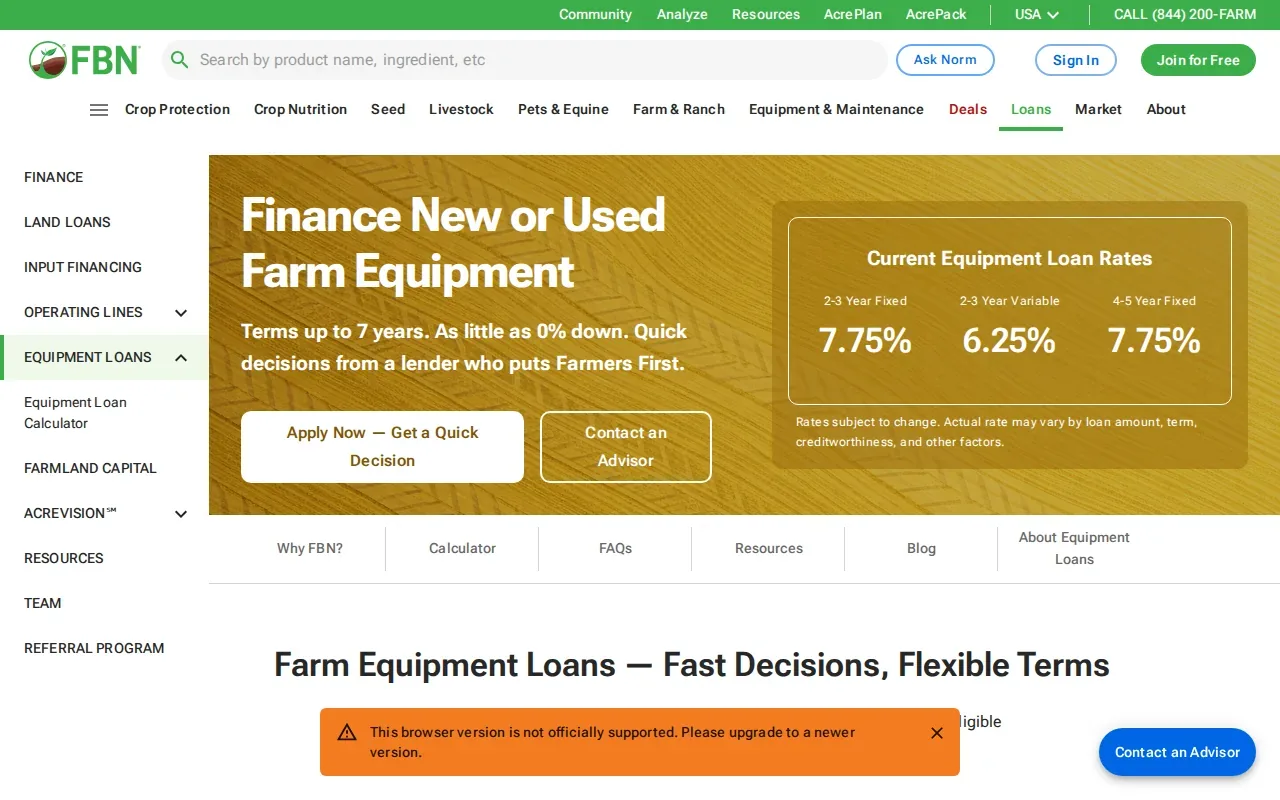
Start with the amount being financed and the payment schedule. Then check the full repayment total and how the due dates line up with your farm’s cash flow. If income is seasonal, payments that fall during a tight stretch can create pressure even when the machine is productive.
For a used tractor or other pre-owned machine, make sure the purchase paperwork describes the equipment clearly. The lender’s review may depend on the asset and transaction. Have the seller’s invoice or purchase details ready, and ask what records are needed before you commit to a purchase date.
It also helps to compare the loan against the machine’s expected working life. A long repayment period can lower each payment, but you don’t want to be paying for equipment after it has stopped serving the job you bought it for. Ask for the actual offer terms and compare them with at least one other route before signing.
Pro Tip: Keep the equipment price, financing cost, and any trade-in value on separate lines when you compare offers. That makes it easier to see what’s driving the total.
5\. Ameris Bank: Bank financing to compare with specialty options
Ameris Bank’s agricultural business loans are aimed at agribusiness owners managing seasonal income and operating costs. Ask whether the specific loan suits your equipment purchase or another cash need.
That distinction matters. A loan for operating expenses may help with costs such as payroll or supplies, but it’s not automatically the same as financing a specific machine. Ask how the loan is structured, what it can fund, and what the payment obligations will be before you compare it with an equipment-specific offer.
Use the table to frame the comparison. It separates each route’s documented fit from the question you should resolve in the written offer.
Option| Documented fit| Question to settle before signing ---|---|--- Dengaro| Online requests from $15,000 to $2 million for new or used business equipment, with application tracking.| What terms does the financing provider approve for your transaction? AgDirect| Farm equipment loans and leases, with terms that vary by equipment type.| What is the total cost after the term, fees, and any down payment? Farm Credit Express| Equipment loans through participating dealerships.| Does the payment schedule fit your farm’s income pattern? Ameris Bank| Agricultural business loans.| Can the loan be used for the machine you’re buying?
For a wider company comparison, Dengaro has a separate roundup of equipment financing companies for U.S. businesses. Keep in mind that your final choice depends on the actual offer, not the name of the lender.
Key Takeaway: Match the loan to the purpose. Equipment-specific financing and general business funding can have different terms and uses.
How to compare farm equipment financing offers
A lender may assess your credit history, time in business, cash flow, the equipment’s value, and the down payment. A lower FICO score doesn’t by itself tell you what terms you’ll receive. Providers review the full application, and different financing routes may weigh each factor differently.
Have your equipment quote or invoice ready. Lenders may also ask for tax returns and financial statements. Before you apply, check that your business details match across the application and supporting records. If your income changes by season, be ready to explain when cash comes in and how you’ll manage payments during slower months.
For a government program comparison, review the eligibility and terms using this online resource. Compare the application process with private financing, especially if you’re working toward a near-term purchase.
Use these checks before you accept an offer:
- Compare the annual rate and total repayment, not only the monthly amount.
- Ask how a trade-in affects the amount financed and any down payment.
- Review payment dates, fees, and the full term in the final documents.
- Consider whether a loan or lease better fits how long you expect to use the machine.
A manufacturer promotion may have a low advertised rate, but it can come with a shorter term or a different rebate. Compare the cash price and financing choice side by side. If you’re weighing tax treatment or depreciation timing, ask a qualified tax professional; a financing offer alone doesn’t settle that question.
When you’re ready to request financing, Dengaro’s online application lets you submit your equipment request and track its status. Start through the online equipment financing application, and review the provider’s final terms before accepting. Approval and funding depend on provider review.
Pro Tip: Keep a copy of the quote, invoice, and financing offer together. You’ll be able to check the equipment price against the amount financed before you sign.
Farm equipment financing FAQ
Can I finance used farm equipment?
Yes, some financing options consider used farm equipment. AgDirect describes financing for new and used agricultural equipment, and Dengaro accepts requests for new or used business equipment subject to provider approval. Eligibility can depend on the machine, seller, business, and financing provider, so share the equipment details before you commit to a purchase.
How much down payment do I need for a farm equipment loan?
The down payment depends on the lender, the equipment, and your application. AgDirect says eligible borrowers might qualify for $0 down, but that isn’t guaranteed for every buyer. Ask for the down payment in the written offer and compare it with the total cost and the working cash your farm needs to keep.
What documents should I prepare for equipment financing?
Start with the equipment description and expected price, plus your business information and owner details. Have the seller’s invoice or purchase details ready. A provider may ask for tax returns or financial statements as part of its review. Requirements vary, so answer follow-up requests promptly and make sure your records match the information in your application.
Is a loan or lease better for farm equipment?
Neither is always better. A loan may suit you if you plan to keep the machine, while a lease may fit a different use period or payment plan. Compare the full cost, payment schedule, and contract terms. If tax treatment affects your decision, ask a tax professional to review the specific arrangement.
How long does approval take?
Timing varies by provider and transaction. AgDirect says most credit decisions are returned within hours, while Farm Credit Express approval might take as little as a few minutes. Those timeframes aren’t guarantees. A provider may need more information or completed documents before it can make a decision or release funds.
Conclusion
For a larger new or used equipment request, start by checking whether Dengaro fits your financing amount and application needs, then compare the provider’s written terms with a farm-focused loan or lease. Your next step is to submit the online application and track its status while you review the offer carefully.