
Best Farm Equipment Financing Rates: 7 Options
Compare farm equipment financing rates and seven options for new or used machinery. See rate factors, terms, fees, and ways to assess total cost.
Farm equipment financing rates can change what a tractor, combine, or used skid steer costs over time. Dengaro lets businesses request $15,000 to $2 million online and track an application, while the options below vary in rate details, credit criteria, and equipment focus.
We analyzed 44 comments and questions from YouTube and Quora about farm equipment financing and found that 39% mentioned interest rates.
Table of Contents
- Dengaro
- Credibly
- National Business Capital
- ArborOne Farm Credit
- AgDirect
- John Deere Financial
- Crest Capital
- Compare the total cost before you sign
- Frequently asked questions
- Conclusion
1\. Dengaro
Dengaro is an online equipment financing application platform for U.S. businesses buying new or used equipment. It’s a fit when you want to request $15,000 to $2 million and keep an eye on your application status as it moves through review.
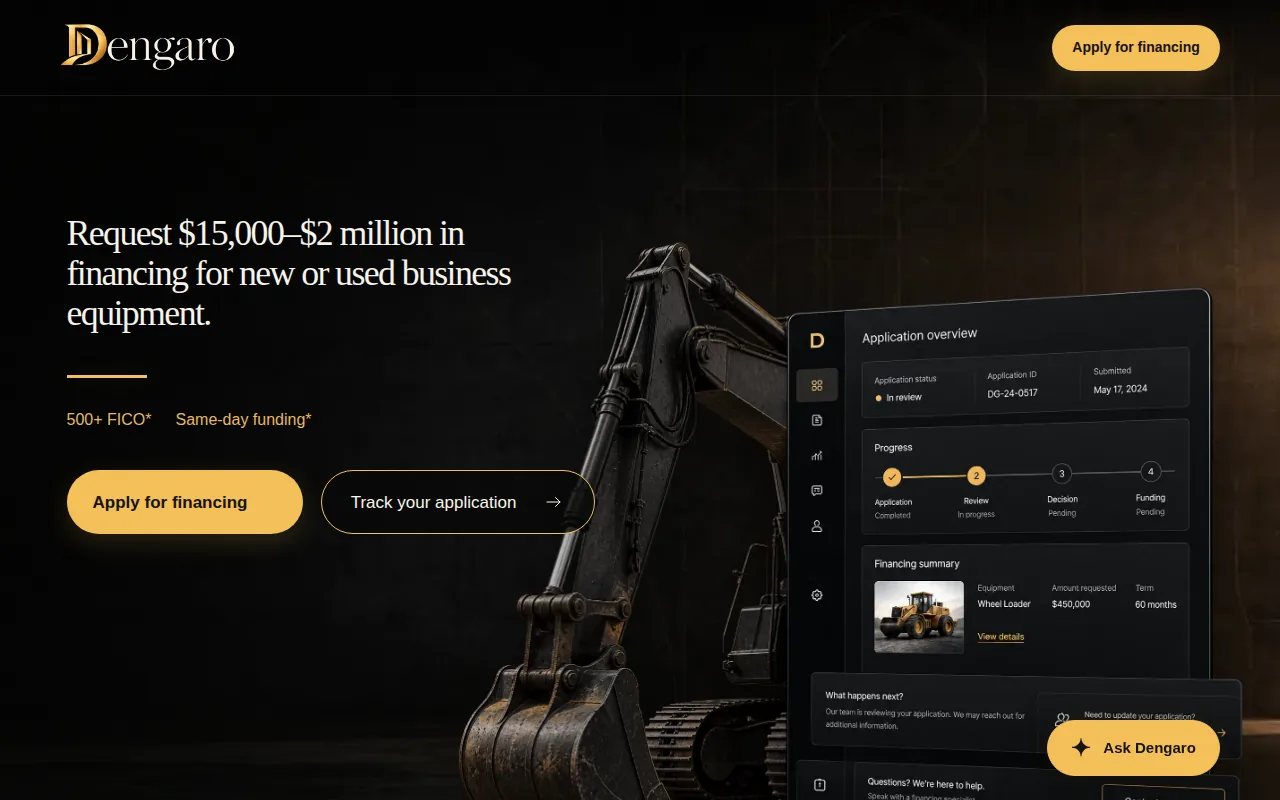
You can apply online and track your application through Dengaro. Requests are subject to provider approval, and final terms depend on the provider and transaction. See the equipment financing details before you decide what amount to request.
That range can suit farm operators financing a major machine, as well as construction contractors seeking an excavator or skid steer. The online status view helps you check progress while you plan around a purchase or repair deadline. It doesn’t guarantee a decision time or approval.
Before applying, have a clear purchase amount in mind. A machine quote gives you a better basis for comparing the financing amount with your cash flow.
2\. Credibly
Credibly is an equipment financing option for businesses facing credit challenges. Its stated minimum credit score is 500, which may make it worth considering if your FICO score is below the threshold some other lenders set.
A lower minimum score doesn’t mean every application will qualify. A lender may also review the business, equipment, and ability to make payments. Ask what rate and payment schedule apply to your specific request, then compare the full repayment amount with your expected cash flow.
This matters when farm income rises and falls with planting or harvest cycles. A payment that looks manageable during a strong month can strain the business during a slower period. Check how often payments are due and whether that timing fits your revenue pattern.
Credibly’s stated score threshold gives you one useful point of comparison. Treat it as an eligibility detail, not a promise of approval or a rate offer.
3\. National Business Capital
National Business Capital is an option for new farmers seeking agriculture equipment loans. Its stated minimum credit score is 550, and funding may occur within 24 hours of approval.
Keep the timing claim in context: funding speed is described as occurring after approval, not from the moment you start an application. Your purchase timeline should allow room for review and any steps needed to complete the transaction.
New farm owners can compare this option with a broader equipment financing request through Dengaro. Before choosing, ask for the amount financed, the payment schedule, and the total repayment figure in writing. Those details help show whether a fast approval path also fits your operating budget.
A 550 score minimum may help you decide whether to ask for a quote. It doesn’t tell you what rate or term you’ll receive, so compare the offer itself.
4\. ArborOne Farm Credit
ArborOne Farm Credit is an agriculture-focused option with a dedicated equipment financing service. It may be a useful name to include when you want to compare a farm-oriented lender with general business financing platforms.
That conversation matters for equipment bought to meet a short seasonal need. A longer term can lower each scheduled payment while increasing the time you carry the debt. Compare the full amount paid over the term, not only the first payment.
Use ArborOne as a comparison point, then check whether the offer’s rate type, fees, and payment dates suit your operation. Those terms matter as much as the lender’s agriculture focus.
5\. AgDirect
AgDirect is powered by Farm Credit and was built to finance agricultural equipment. Its program covers equipment purchased through a dealer, at an auction, or from a private seller, with purchase, lease, and refinancing options.
AgDirect lists fixed and variable rates, with terms generally ranging from two to seven years and up to 10 years for pivots. Fixed payments can make budgeting easier because the rate stays the same. With a variable rate tied to the prime index, payments can adjust when the index changes. Published rate data reports selected interest rates, including the bank prime loan rate.
AgDirect says most applications receive a credit decision in seconds, with a goal of processing applications within three business hours. Its stated down payment range is generally 0% to 30%, subject to approval. A nominal documentation fee may apply, and servicing actions may also have a fee.
Private-party and auction purchases may have a minimum purchase price. If you’re buying at auction, check the minimum and approval timing before you bid.
6\. John Deere Financial
John Deere Financial offers financing for used agricultural equipment sold through a local John Deere dealer. It’s a natural option to compare if you’re buying eligible used machinery through that dealer network.
Dealer financing can make it easier to discuss the machine and financing in the same purchase process. Still, compare the financing quote with any cash price or other available offer. A low payment can come from a longer term, so ask for both the term and total repayment amount.
For used equipment, inspect the machine’s condition and expected working life before choosing a term. You don’t want to keep making payments long after the machine has reached the end of its useful role on your farm.
Confirm that the specific used machine and sale qualify before you plan around this option.
7\. Crest Capital
Crest Capital provides equipment financing for business purchases. The reported starting interest rate is 6.75% for small loans, with terms from 24 to 84 months and financing up to $500,000. Its funding decision may come the same day.
That rate is an interest-rate starting point, not necessarily the APR or the total cost of your loan. APR accounts for interest and certain costs tied to borrowing. Compare the written APR and total repayment rather than relying on a starting rate alone. Annual percentage rate is a standard way to express borrowing costs over a year.
The $500,000 maximum may fit a smaller machinery purchase, but it’s below Dengaro’s stated $2 million request ceiling. Check the amount you need and ask how the final term, fees, and payment frequency change the total cost.
What to compare| Crest Capital detail| Why it matters ---|---|--- Starting interest rate| 6.75% for small loans| Confirm the actual APR and rate in your written offer. Term range| 24 to 84 months| A longer term can lower scheduled payments but extend repayment. Maximum amount| Up to $500,000| Check that the amount covers the machine and related purchase costs. Decision timing| Same-day lending decision| A decision is not the same as funding or final approval.
Compare the total cost before you sign
There isn’t one best rate for every farm. A lender’s offer can depend on your credit, the machine, the term, and the full transaction. Compare APR alongside total repayment, payment frequency, and fees. A low advertised rate can still cost more if fees are high or a cash discount disappears when you finance.
Ask whether the loan is secured by the equipment. With secured financing, a lender may file a UCC record that gives it a claim tied to the equipment if you don’t repay. A filing or documentation fee may add to the cost. Read the agreement and ask which fees apply in your state and to your transaction.
Paying cash avoids interest, but it also uses funds your business might need for payroll, fuel, repairs, or seasonal expenses. Compare any cash discount with the cost of financing and the value of keeping cash available. Don’t assume a zero-percent offer is free until you check the purchase price and fees.
To estimate the payment, use the amount financed, interest rate, and number of payments. Then compare that payment with cash flow during a slower month, not only during peak season. Dengaro’s equipment financing calculators can help you test different amounts and terms before you apply.
Pro Tip: Ask each lender for the same loan amount and term. That makes it easier to compare APR, fees, and total repayment on equal terms.
Before you submit an application, gather a machine quote and basic business details. Your lender may ask about the equipment, your business finances, or your credit. You can apply for equipment financing online with Dengaro and track your application status. Approval and final terms depend on the financing provider’s review.
Next step: Write down your target purchase price and the highest payment your farm can handle in a slow month, then request comparable offers.
Frequently asked questions
What affects farm equipment financing rates?
Rates can depend on your credit profile, the equipment, the amount financed, and the repayment term. The lender’s rate type and fees also affect the total cost. Ask for the APR and total repayment amount in writing. That gives you a clearer comparison than a starting interest rate or monthly payment alone.
Is it better to pay cash or finance farm equipment?
It depends on the cash discount, financing cost, and how much working capital your farm needs. Paying cash avoids loan interest, but it can leave less money for seasonal costs or repairs. Compare the cash price with the full financed cost, including fees, then consider whether keeping cash on hand is worth that difference.
Can I finance used farm equipment?
Yes, some options in this shortlist finance used agricultural equipment. Dengaro accepts requests for new or used business equipment, and John Deere Financial describes financing for eligible used agricultural equipment sold through a local John Deere dealer. Confirm that the machine and seller meet the provider’s rules before you commit to a purchase.
What fees should I check in an equipment financing offer?
Ask about documentation, processing, and UCC filing fees, along with any fee tied to servicing the loan. Confirm which fees apply to your transaction and whether they’re included in the amount financed. Then compare the APR and total repayment with another offer for the same amount and term.
Conclusion
For a broad online application with status tracking and requests from $15,000 to $2 million, start by comparing Dengaro with a farm-focused option that fits your purchase. Gather the equipment quote, then request written terms and compare APR, fees, and total repayment before signing.