
Best Machinery Loans: 5 Options for Businesses
Compare machinery loans for U.S. businesses financing new or used equipment, from excavators and skid steers to manufacturing machines.
A machinery purchase can tie up cash your business needs for payroll, fuel, or its next job. These five financing options give you different starting points, with Dengaro first for requests from $15,000 to $2 million on new or used business equipment.
Compare the equipment each option can cover, the information you may need, and what to confirm before you commit.
Table of Contents
- Dengaro
- Fora Financial
- Fundible
- Business Equipment Financing by First Citizens
- Ameris Bank
- Machinery Loan Options Compared: Product Fit, Eligibility, and What to Confirm
- Buyer’s Checklist: Cash Flow, Used Equipment, and Total Financing Cost
- Frequently Asked Questions
- Conclusion
1\. Dengaro
Dengaro is an online equipment financing application platform for U.S. businesses requesting $15,000 to $2 million for new or used equipment. It fits owners who want to submit one online request and keep track of application status as it moves through review.
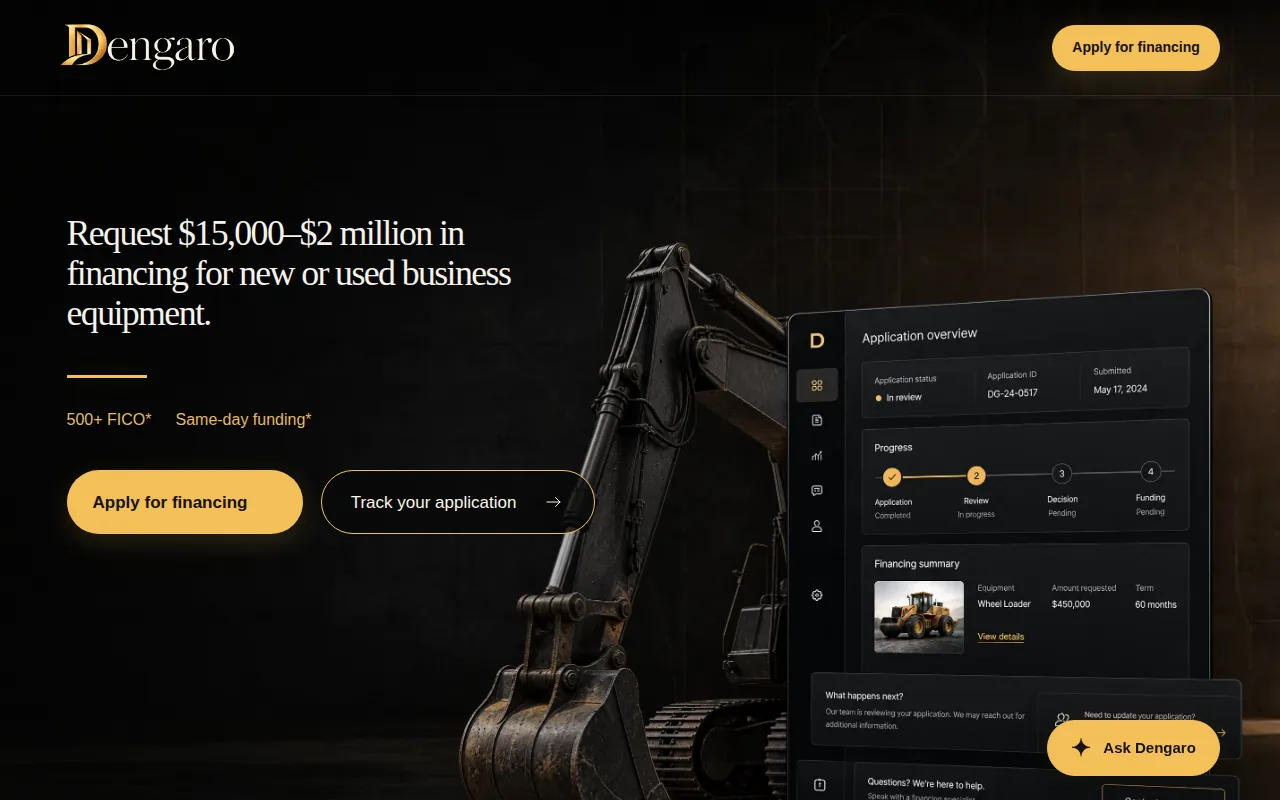
That range can suit a contractor looking at an excavator or skid steer, as well as businesses financing other work equipment. Dengaro accepts requests for both new and used machines. The financing provider reviews the business, owner, equipment, and transaction, then makes any credit decision and determines the terms.
When you apply, prepare the equipment description and expected price, then share your business and owner details. You can review Dengaro equipment financing before starting. Application status tracking helps you see recorded milestones and requests, but it isn't a promise of approval or funding by a specific date.
For a used machine, gather its make, model, year, hours if available, condition, seller details, and a clear quote. If you're weighing a construction purchase, construction equipment financing can help you think through the machine and project details to prepare.
Key Takeaway: Dengaro is a fit when your request falls within its stated range and you want an online application with status tracking.
2\. Fora Financial
Fora Financial is a business financing provider with several financing types, including financing for equipment purchases. It may be worth investigating if your business is relatively new: the stated minimum time in business is six months for some financing types.
Fora Financial lists business funding up to $1.5 million, and its site describes equipment financing as a way to preserve working capital for day-to-day operations. Its listed minimum credit score is 570. Those details are starting points, not a promise that a specific equipment request will qualify. The financing type, revenue profile, and full application can affect the decision.
Some long-term financing applicants need at least six months in business. The provider also says approval decisions can take as little as four hours after it receives the necessary documents. That is an approval decision timeline, not a guarantee that funds will reach you then. Review the specific offer, payment schedule, fees, and any early-pay terms before deciding.
3\. Fundible
Fundible is an online lender specializing in flexible financing for business owners with different credit profiles. Its stated minimum credit score is 500, which may make it worth considering if your FICO score is below another lender’s stated threshold.
A minimum score is only one part of a financing review. Your cash flow matters because it helps show whether the business can manage payments while covering operating costs. Prepare accurate revenue figures and be ready to describe how the machine will support your work, such as moving more material on a construction site or replacing a production bottleneck.
Fundible’s stated financing amount range reaches $10 million. Treat that as a broad business financing range rather than an assurance that a machinery purchase at that amount will qualify. Ask which financing product applies to your purchase, what equipment is eligible, and whether the offer requires a down payment or other upfront funds.
If you're comparing credit requirements, compare the full terms too. A score threshold alone doesn't tell you the payment size, total cost, or whether the proposed term fits the useful working life of the machine.
4\. Business Equipment Financing by First Citizens
Business Equipment Financing by First Citizens is a dedicated equipment financing and leasing product. First Citizens describes options for new, used, and custom-built equipment, along with vehicles, and says its equipment financing spans industries that include heavy equipment.
This may suit a business that wants to discuss a bank’s equipment-focused financing or leasing options. The bank says financing can help preserve cash flow and notes that some structures may provide 100% financing. That is a stated potential benefit, not a commitment to finance every purchase in full. Your offer depends on the transaction and approval.
First Citizens also describes pre-approved lines of credit for annual capital spending or more than one purchase. That structure may be relevant if your business expects equipment needs across the year, rather than one standalone machine. Ask whether the line is available for your business and how it would work for the equipment you plan to buy.
Tax treatment can depend on how financing is structured. First Citizens says a term loan or capital lease may allow depreciation and recommends discussing qualified financing with a financial professional. Ask your tax adviser how ownership, lease terms, and the timing of deductions apply to your situation.
5\. Ameris Bank
Ameris Bank is a bank financing option to investigate for an equipment purchase. It may be a starting point if you prefer to ask a bank about financing for a business asset and compare the response with other options on this list.
Before you spend time on an application, ask whether the bank's available product fits the exact machine and transaction. Be ready to explain whether the equipment is new or used, its purchase price, and how your business will use it. For a used excavator or skid steer, keep the seller’s quote and the machine’s identifying details close at hand.
Ask for the proposed amount, term, payment schedule, rate, fees, and any down payment in writing. Also confirm whether the equipment itself secures the financing and what happens at the end of a lease, if the offer is structured as one. Those details let you compare a bank offer with an online application or another equipment-focused product on the same basis.
Ameris Bank is a name to check, not a reason to assume the terms suit your cash flow. Match any payment to the months when the machine will earn revenue, including slower periods.
Machinery Loan Options Compared: Product Fit, Eligibility, and What to Confirm
Use this table to narrow the list by the facts each provider makes available. Ask every provider for transaction-specific terms before you compare offers.
Option| Useful starting point| Details to confirm ---|---|--- Dengaro| $15,000 to $2 million; new or used equipment; online application and status tracking| Provider approval, equipment fit, offer terms, and any upfront payment Fora Financial| Six months in business for some financing types; stated minimum score of 570| Which product covers equipment and the payment terms for your request Fundible| Online lender; stated minimum score of 500| Product fit, amount, rate, term, and any down payment Business Equipment Financing by First Citizens| Equipment financing and leasing for new or used equipment| Availability, financing structure, tax treatment, and final terms Ameris Bank| Bank option to investigate for equipment financing| Eligible asset, application needs, payment schedule, and full cost
Machinery loans are tied to an equipment purchase, while a general business loan may be designed for broader business expenses. Neither structure is automatically cheaper. Compare the annual cost, fees, payment timing, collateral terms, and what you owe at the end of the agreement.
Leasing can also differ from a loan. Some leases include an end-of-term purchase option or a fair-market-value payment. Make sure you know whether you will own the machine, return it, or need to make another payment when the term ends.
Pro Tip: Compare offers using the same purchase price and term assumptions. A lower monthly payment can still mean a higher total cost or an end-of-term payment.
Buyer’s Checklist: Cash Flow, Used Equipment, and Total Financing Cost
Start with the payment your business can carry in a slow month, not only the revenue you expect once the machine is busy. A lender may review business revenue, credit history, and the equipment transaction. A broader business loan option may not fit every equipment need, so confirm whether it suits your purchase.
For a used machine, check the condition and identify the seller. Keep the quote itemized so the machine price is separate from attachments, delivery, or other costs. If you're looking at a used machine specifically, used equipment financing details can help you prepare the asset information for review.
Gather business and owner information, recent financial records if requested, and the equipment quote. Dengaro’s online application lets you apply for equipment financing and track your application status. Then compare the payment schedule, total repayment, fees, collateral, and any end-of-term obligation. If a tax deduction may affect the purchase decision, discuss current rules with your tax adviser; the Section 179 equipment financing resource is a starting point for that conversation.
Key Takeaway: A machine is affordable only if the full payment obligation fits your business cash flow, including the upfront cost and any final payment.
Frequently Asked Questions
What do lenders look at for machinery financing?
Lenders may review your credit profile, business history, revenue, and the equipment being purchased. They may also ask for business and owner details plus a seller quote or other equipment records. Requirements vary by provider and financing product, so a credit score alone cannot confirm approval, the amount available, or the final terms.
Can I finance used machinery?
Yes, used machinery may be eligible, depending on the provider and the specific asset. Prepare the make, model, year, condition, and available operating-hour information. Keep seller details and an itemized quote ready too. The provider reviews the equipment and transaction, so submitting a request does not guarantee that the machine will qualify.
How much can I finance for an excavator or skid steer?
The amount depends on your request, the machine, your business profile, and the provider’s decision. Dengaro accepts equipment financing requests from $15,000 to $2 million for new or used business equipment. That range is not an approval promise; the provider determines whether your transaction qualifies and what terms it can offer.
Is equipment financing better than a business loan?
It depends on what you’re buying and the terms offered. Equipment financing is connected to an equipment purchase, while a general business loan may cover broader business needs. Compare the rate, fees, payment schedule, collateral, and end-of-term terms. Don’t assume equipment financing will always cost less or require less documentation.
How do I apply for equipment financing?
Gather the equipment details, expected purchase price, seller quote, and business information first. Dengaro lets you submit an application online and track its status. The financing provider reviews the request and makes the credit decision. Approval and funding are separate steps, and timing depends on provider approval and completed transaction requirements.
Conclusion
For a U.S. business seeking $15,000 to $2 million for new or used equipment, Dengaro is a clear first place to start: apply online and track your application as it moves through review. Prepare the machine details and seller quote before you begin.