
Best Restaurant Equipment Financing Companies
Compare restaurant equipment financing companies by funding needs, equipment leasing, credit fit, and application tracking before you apply.
A broken refrigerator or worn-out oven can throw off a whole shift, but paying cash for a replacement can squeeze working capital. Restaurant equipment financing lets you spread an equipment purchase over time. Here are seven companies and options to compare, starting with Dengaro for its clear financing range and online application tracking.
Table of Contents
- Dengaro — Online equipment financing with application tracking
- Equinox Funding — A speed-focused option
- Crest Capital — For stronger credit profiles
- Balboa Capital — For larger financing packages
- Taycor Financial — Lease-style equipment financing
- National Funding — Broader business financing options
- TimePayment — Vendor-connected financing to compare
- Restaurant equipment financing FAQ
- Conclusion
1\. Dengaro — Online equipment financing with application tracking
Dengaro is an online equipment financing application platform for U.S. businesses. It lets you request $15,000 to $2 million for new or used business equipment, apply online, and track your application. Financing is subject to provider approval.
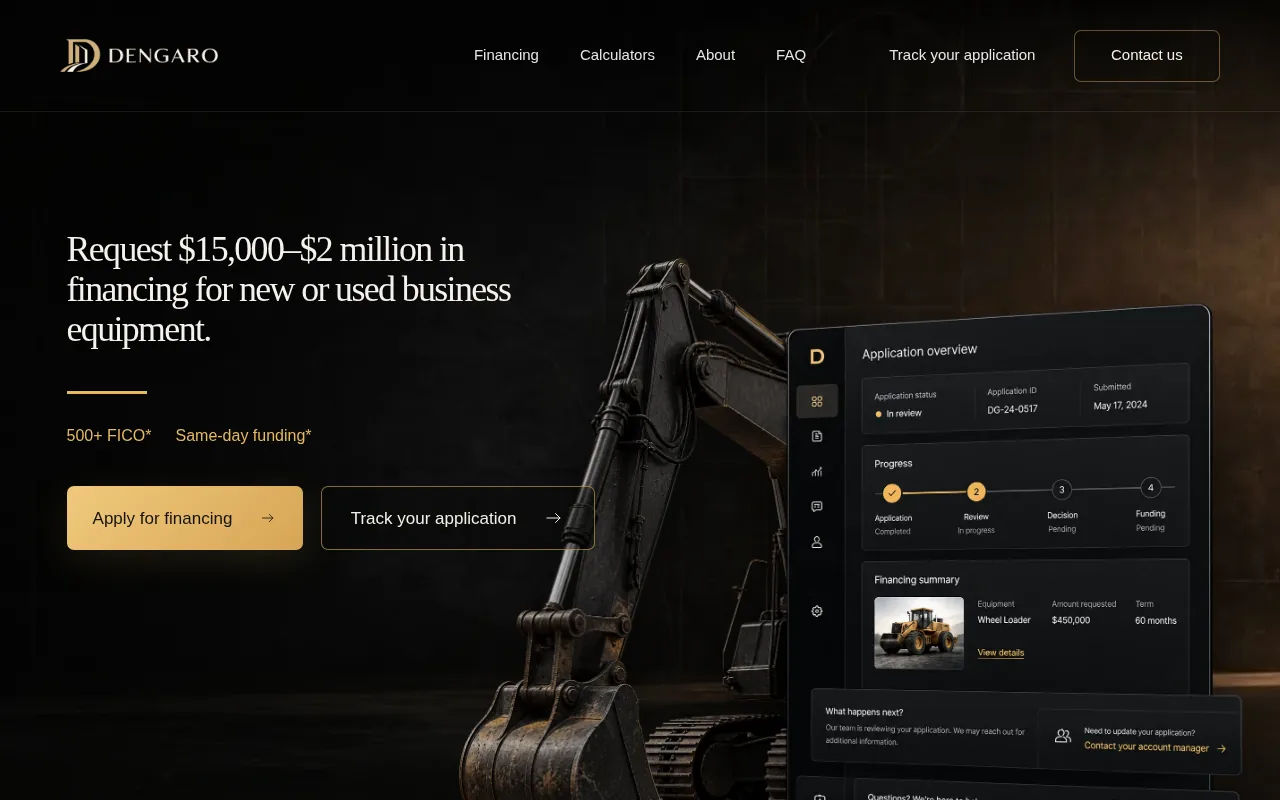
For a restaurant owner, that range gives you an early way to judge whether a request might fit. It may be relevant for a larger kitchen buildout or a used commercial machine purchase, though the financing provider reviews the complete request and the equipment. Dengaro is a financing broker and platform, not the lender. Participating providers make credit decisions and set final terms.
Equipment financing can help you keep cash available for payroll, food orders, or a slow week instead of paying the full equipment cost at once. The equipment financing details explain Dengaro’s range and how its platform works. When you apply, you can use Dengaro’s online application and then track your application status in its applicant workspace.
That status view can help you see what milestone comes next. It doesn’t promise approval or a funding date.
2\. Equinox Funding — A speed-focused option
Equinox Funding is a restaurant equipment financing provider described as an option for owners who value fast approvals. That may matter when a failed oven or refrigeration unit is disrupting service and waiting too long could affect daily operations.
Speed claims still need context. The timing of any financing depends on the request, the equipment, and the information a provider needs to review. Treat “fast approvals” as a reason to ask about the next steps, not as a promise that funds will arrive by a set date.
Before moving ahead, ask how the provider will assess your business cash flow and the equipment’s condition if it’s used. A complete invoice or quote can help clarify what you’re buying and how much you need to finance. Compare the payment and total cost with your expected equipment life, especially if the machine is essential to daily service.
For an urgent replacement, the useful question isn’t only how quickly a decision may come. It’s whether the proposed payment fits the restaurant after the immediate repair or purchase is done.
3\. Crest Capital — For stronger credit profiles
Crest Capital is a recognized equipment financing name that may suit borrowers with stronger credit profiles. If your restaurant has an established record of sales and a solid credit history, it may be one option to compare for an equipment purchase.
Credit affects more than a yes-or-no decision. A provider may weigh your personal and business credit alongside cash flow, time in business, and the equipment itself. A stronger profile can improve the terms available, but it doesn’t guarantee approval or a particular rate.
Think through the monthly payment in the context of your actual sales pattern. A restaurant that earns more during certain seasons should check whether payments remain manageable in slower months. You’ll also want to confirm what documents the provider needs, such as an equipment quote or business financial records.
Use a written offer to compare the payment schedule, fees, term, and any security interest. Don’t judge an offer by the monthly payment alone.
4\. Balboa Capital — For larger financing packages
Balboa Capital is an option for businesses seeking larger equipment financing packages. That may fit a restaurant planning a significant kitchen upgrade or replacing several key pieces at once.
A larger request makes it especially important to match the financing amount to a clear purchase list. Separate equipment you need to keep service running from items that can wait. Then check whether the proposed payments leave enough cash for regular operating needs.
Restaurant equipment can include ovens, refrigeration, dishwashers, and fixtures. Eligibility depends on the specific transaction and provider review, so confirm that the equipment and seller meet the provider’s criteria. For used equipment, be ready to describe its age, condition, and price.
Review the full terms before accepting an offer.
5\. Taycor Financial — Lease-style equipment financing
Taycor Financial is a company to consider if you’re comparing equipment leasing structures. Leasing can work differently from a loan, so focus on what happens at the end of the agreement, not only on the monthly amount.
With a loan, you generally pay toward ownership of the equipment, subject to the agreement and any secured interest. A lease may let you use equipment for a set term, with options that depend on its contract. Some leases end with a return, while others may include a purchase option. Confirm those terms in writing before signing.
Leasing may appeal if you expect to replace or upgrade a machine before it wears out. But the cost and end-of-term choices matter. Ask who handles repairs, whether maintenance is included, and what charges could apply if you return equipment.
For a restaurant weighing an equipment lease against a purchase loan, compare total payments and ownership rights over the full term. A lower monthly payment doesn’t always mean a lower total cost.
6\. National Funding — Broader business financing options
National Funding offers broader business financing solutions for established restaurant operators.
That split can help you sort an equipment cost from a broader cash need. If the request covers a specific machine, equipment financing may be the closer fit. If you’re also managing payroll or other costs, ask how each option works and whether its payment schedule matches your cash flow.
When applying for equipment financing through Dengaro, you can use its online application and track your application status. Prepare a clear equipment quote and a view of recent business deposits so you can explain the amount you need. The final offer and approval depend on the provider’s review.
Before comparing offers, check the rate and total repayment cost as well as the monthly bill. These factors that shape equipment financing rates can help you frame questions about cost and terms.
7\. TimePayment — Vendor-connected financing to compare
TimePayment is associated with dealer and vendor financing relationships. That can be worth checking when the restaurant equipment seller already works with a financing provider. The seller may be able to explain how the financing request connects to the equipment purchase.
Vendor-linked financing can make the purchase steps feel more direct, but review the agreement just as carefully as you would a separate financing offer. Confirm who provides the financing, what the payment schedule is, and whether the contract includes ownership or return options.
TimePayment is also described as an option for more challenged credit profiles and smaller financing amounts. Credit is only one part of a review: your business cash flow and the equipment details can matter too. Don’t assume a particular credit score will lead to approval.
Option| May fit when you need| Compare before applying ---|---|--- Dengaro| A $15,000 to $2 million request and online application tracking| Provider approval and final terms Equinox Funding| A speed-focused approval process| Expected review and funding timing Crest Capital| A financing option for a stronger credit profile| Payment, term, and total cost Balboa Capital| A larger equipment package| Equipment eligibility and full terms Taycor Financial| A lease-style structure| Maintenance and end-of-term choices National Funding| Equipment financing or wider restaurant funding needs| Which product fits the expense TimePayment| A vendor-connected option or smaller request| Provider, agreement, and ownership terms
Use this as a starting point, not a substitute for reading the offer. The restaurant’s cash flow and the equipment’s useful life should guide the final choice.
Pro Tip: Ask for the full payment schedule and end-of-term terms in writing. Compare those details before you focus on the monthly payment.
Restaurant equipment financing FAQ
How does restaurant equipment financing work?
Restaurant equipment financing lets a business spread the cost of eligible equipment over time. A provider reviews the business, the requested amount, and the equipment before making an offer. With a loan, the lender may use the equipment as collateral, and ownership terms follow the agreement. Check the payment schedule and total cost before accepting.
Can I finance used restaurant equipment?
Yes, used restaurant equipment may be considered, but approval depends on the asset, seller, business, and provider criteria. Be ready to share the equipment’s description, purchase price, and condition. Ask the provider how it treats used equipment and whether the seller must meet any requirements. Submitting an application doesn’t guarantee approval or funding.
Is it better to lease or finance restaurant equipment?
It depends on whether you want ownership and how long you expect to use the equipment. Financing through a loan may lead to ownership after repayment, depending on the contract. A lease may include a return or purchase option at term end. Compare the total payments, repair terms, and end-of-term choices rather than choosing by monthly cost alone.
Can equipment financing interest be tax deductible?
It may be, but the tax treatment depends on your business and financing agreement. Ask a qualified tax professional how the purchase and contract apply to your return.
What should I prepare before applying?
Prepare the equipment description and expected price, along with your business details and owner information. A quote or invoice can help explain the amount requested. Dengaro’s online application lets you submit a financing request, then track its status in the applicant workspace. Review each authorization before signing, and remember the financing provider makes the credit decision.
Conclusion
If you want a stated financing range and a way to follow your application, start with Dengaro, while keeping approval and final terms subject to provider review. Compare the full cost and ownership terms before you commit. When you’re ready, apply online for equipment financing and track your application status.